SparseSolvers-IRLS
A modified Iteratively Reweighted Least Squares solver for non-convex sparse regression.
- Status
- Private repo
- Year
- 2025
- Stack
- Python, NumPy
Why I built it
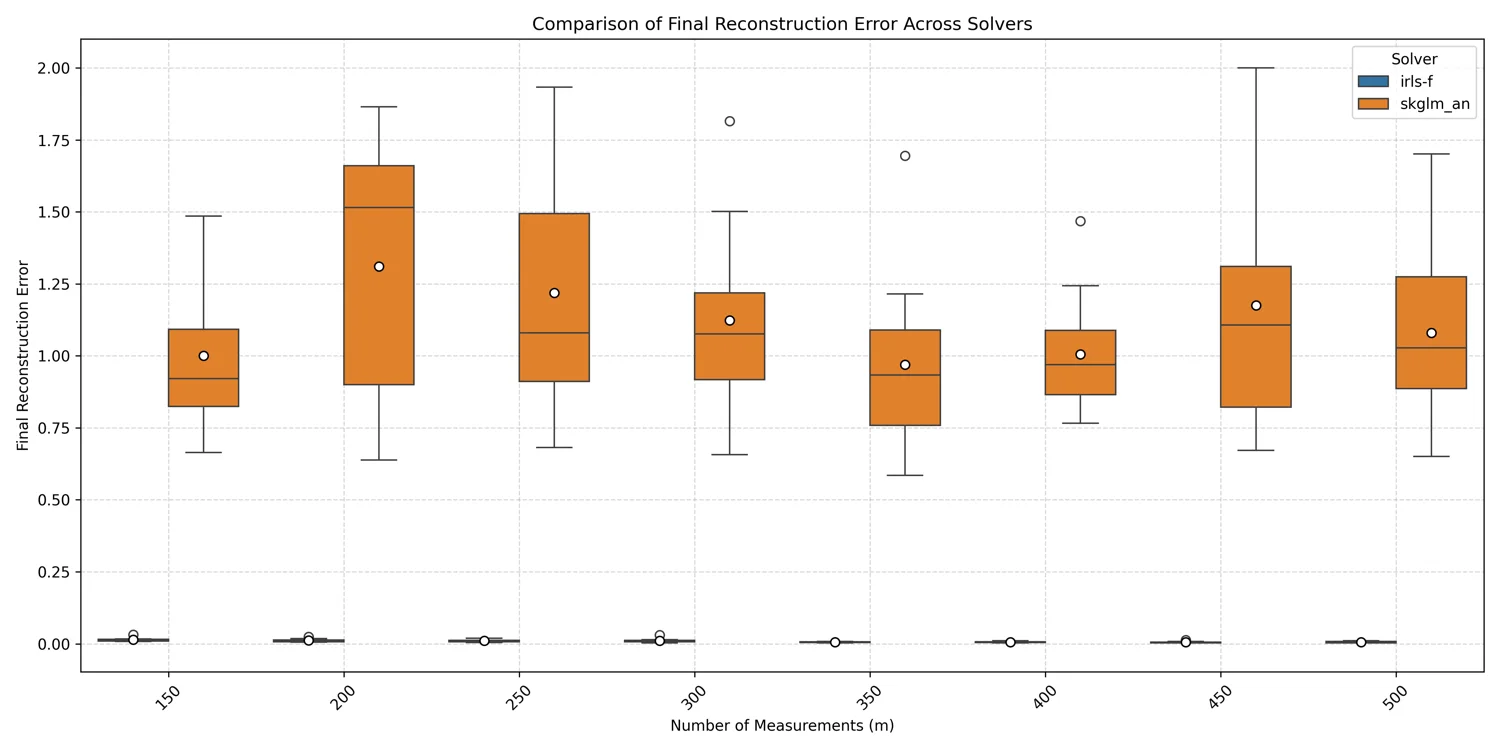
Standard IRLS struggles to converge under a nonconcave fractional penalty. This adds adaptive weighting and a dynamic smoothing term to stabilize it.
How it works
Benchmarked against other sparse solvers with BenchOpt.